From 1 January 2026, the total CPF (Central Provident Fund) contribution for employees aged 55 and below is 37% of monthly wages, and the Ordinary Wage ceiling rose to S$8,000.
Your CPF contribution is a monthly payment into your CPF accounts, split between an employee share deducted from your pay and an employer share paid on top. It covers Singapore Citizens and Permanent Residents (PRs) working in Singapore, including part-time and casual staff.
Here are the 2026 rates by age, the wage ceilings, worked examples at three salaries, PR rates and the changes that start on 1 January 2027.
At a glance
- Age 55 and below: you pay 20%, your employer pays 17%, total 37% of wages.
- CPF applies to monthly Ordinary Wages up to S$8,000, so the most you pay is S$1,600 a month.
- Bonuses attract CPF up to an annual cap of S$102,000 minus your Ordinary Wages subject to CPF.
- From 1 January 2027, total rates rise to 35.5% for ages above 55 to 60 and 26% for above 60 to 65.
- New PRs pay lower graduated rates in their first two years, then full rates from year three.
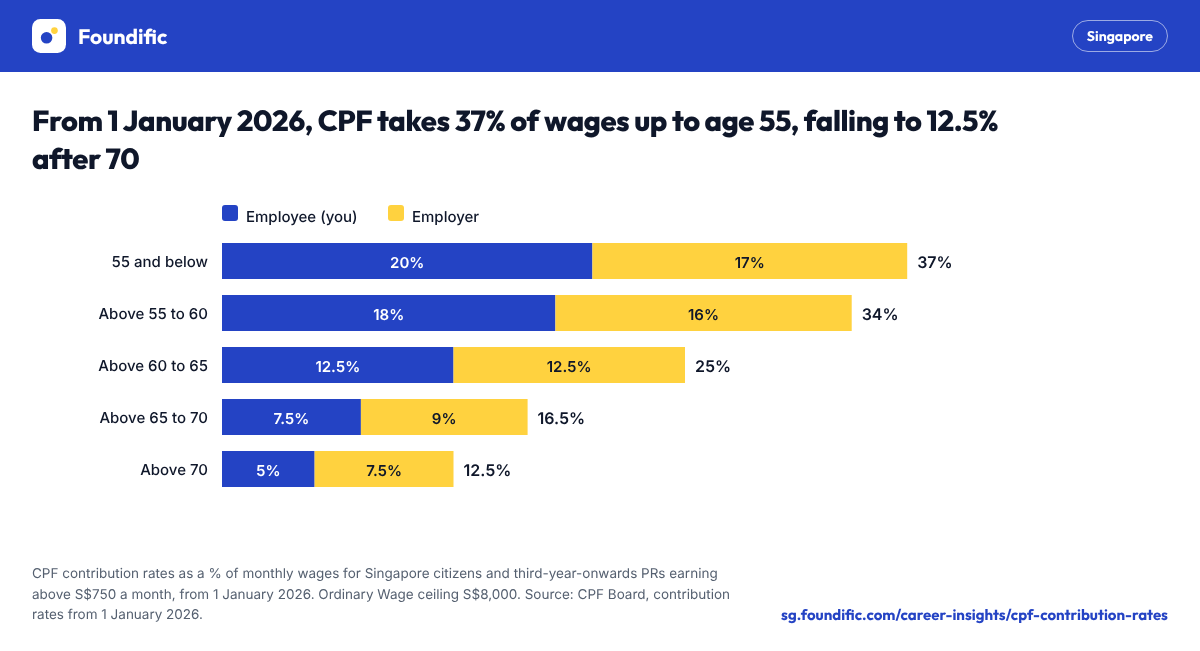
CPF contribution rates for 2026 by age
For monthly wages above S$750, the total CPF contribution ranges from 37% at age 55 and below to 12.5% above age 70. Your employee share is deducted from your salary; your employer's share is paid on top.
| Your age | Employer | Employee (you) | Total | Max employee share a month | Max total a month |
|---|---|---|---|---|---|
| 55 and below | 17% | 20% | 37% | S$1,600 | S$2,960 |
| Above 55 to 60 | 16% | 18% | 34% | S$1,440 | S$2,720 |
| Above 60 to 65 | 12.5% | 12.5% | 25% | S$1,000 | S$2,000 |
| Above 65 to 70 | 9% | 7.5% | 16.5% | S$600 | S$1,320 |
| Above 70 | 7.5% | 5% | 12.5% | S$400 | S$1,000 |
Rates and caps are from the CPF contribution rate table effective 1 January 2026. The monthly maximums apply to Ordinary Wages; bonuses are counted separately.
These rates apply to Citizens and to PRs from their third year of PR status. Employer rates are the total minus the employee share.
CPF rates if you earn S$750 or less
Below S$750 a month, CPF is phased in. If you earn S$50 or less, no CPF is payable; between S$50 and S$500, only your employer contributes.
| Monthly total wages | Employer pays | You pay (age 55 and below) |
|---|---|---|
| S$50 or less | Nil | Nil |
| Above S$50 to S$500 | 17% of total wages | Nil |
| Above S$500 to S$750 | 17% of total wages | 0.6 x (total wages minus S$500) |
| Above S$750 | 17% | 20% |
For older workers, the employer rate in the middle bands follows the age band (16%, 12.5%, 9% and 7.5%), and the employee multiplier drops to 0.54, 0.375, 0.225 and 0.15 in the same rate table.
The Ordinary Wage and Additional Wage ceilings
CPF is only charged on monthly Ordinary Wages (OW) up to S$8,000. Additional Wages (AW), such as bonuses, attract CPF up to a yearly cap.
Ordinary Wages are wages for work in a month that are payable by the 14th of the following month, such as your monthly salary. Everything else, such as an annual performance bonus, is Additional Wages.
The OW ceiling has risen four times since 2023:
| Period | OW ceiling a month |
|---|---|
| Up to 31 August 2023 | S$6,000 |
| 1 September to 31 December 2023 | S$6,300 |
| 1 January to 31 December 2024 | S$6,800 |
| 1 January to 31 December 2025 | S$7,400 |
| From 1 January 2026 | S$8,000 |
Source: CPF Board, OW ceiling. The annual salary ceiling stays at S$102,000.
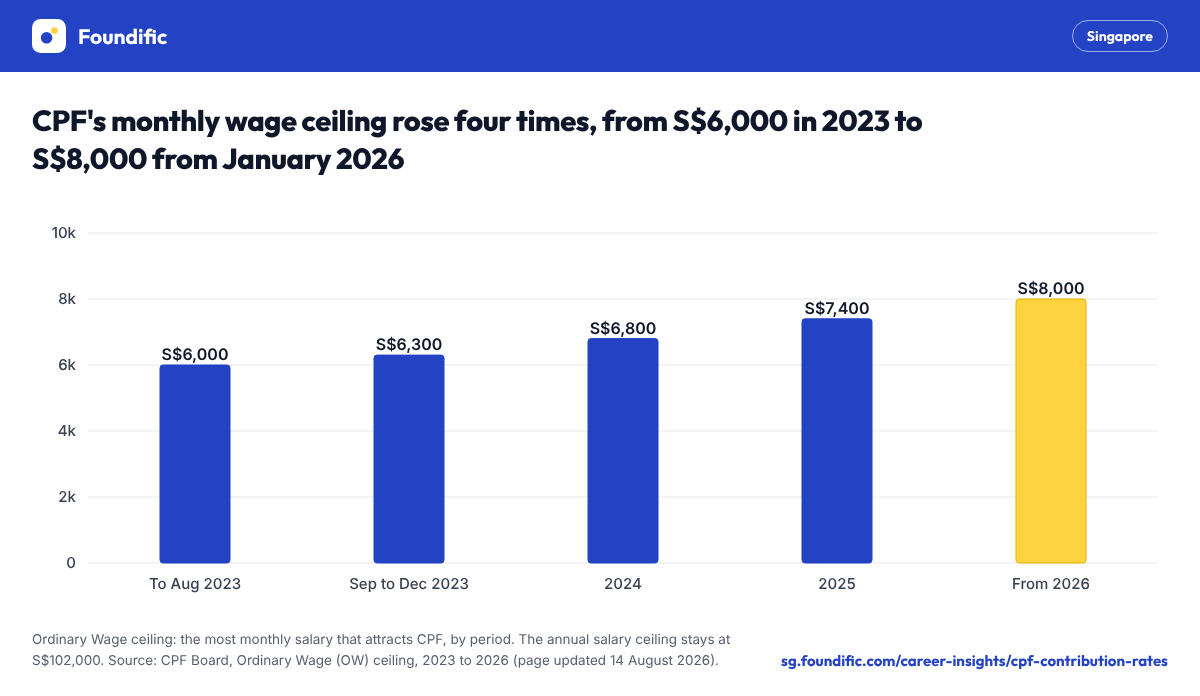
The AW ceiling is S$102,000 minus the total OW subject to CPF for the year. If you earn S$8,000 or more every month, your OW subject to CPF is S$96,000, so only S$6,000 of bonuses attract CPF.
The bonus take-home calculator applies this ceiling to your own bonus. For more on bonus treatment, see our guide to AWS and bonuses.
Where your CPF contribution goes: OA, SA, RA and MA
Your CPF contribution is split across the Ordinary Account (OA), Special Account (SA) or Retirement Account (RA), and MediSave Account (MA). Younger workers get more in the OA; older workers get more in the RA and MA.
| Your age | OA | SA (RA from 55) | MA | Total |
|---|---|---|---|---|
| 35 and below | 23% | 6% | 8% | 37% |
| Above 35 to 45 | 21% | 7% | 9% | 37% |
| Above 45 to 50 | 19% | 8% | 10% | 37% |
| Above 50 to 55 | 15% | 11.5% | 10.5% | 37% |
| Above 55 to 60 | 12% | 11.5% (RA) | 10.5% | 34% |
| Above 60 to 65 | 3.5% | 11% (RA) | 10.5% | 25% |
| Above 65 to 70 | 1% | 5% (RA) | 10.5% | 16.5% |
| Above 70 | 1% | 1% (RA) | 10.5% | 12.5% |
Figures are percentages of your wage, worked out from the 2026 allocation ratios. From age 55, the SA has closed, so SA contributions go to your RA up to the Full Retirement Sum, and to your OA after that (CPF allocation rates).
Worked examples at three salaries
Multiply your monthly wage (capped at S$8,000) by the total rate and your employee rate, then apply CPF's rounding rules. The total is rounded to the nearest dollar, your share is rounded down, and your employer pays the difference.
Example 1: S$3,500 a month, age 30
- Total: S$3,500 x 37% = S$1,295
- You pay: S$3,500 x 20% = S$700
- Employer pays: S$1,295 minus S$700 = S$595
- Pay after employee CPF: S$3,500 minus S$700 = S$2,800
Example 2: S$5,775 a month, age 30
S$5,775 is the 2025 median gross monthly income of full-time employed residents (including employer CPF).
- Total: S$5,775 x 37% = S$2,136.75, rounded to S$2,137
- You pay: S$5,775 x 20% = S$1,155
- Employer pays: S$2,137 minus S$1,155 = S$982
- Pay after employee CPF: S$4,620
- Into your accounts: about S$1,329 OA, S$346 SA and S$462 MA
Example 3: S$10,000 a month, age 30
- CPF wage: capped at S$8,000
- Total: S$8,000 x 37% = S$2,960
- You pay: S$8,000 x 20% = S$1,600
- Employer pays: S$1,360
- Pay after employee CPF: S$10,000 minus S$1,600 = S$8,400
Example 4: S$5,775 a month, age 58
- Total: S$5,775 x 34% = S$1,963.50, rounded to S$1,964
- You pay: S$5,775 x 18% = S$1,039.50, rounded down to S$1,039
- Employer pays: S$925
- Pay after employee CPF: S$4,736
To run your own numbers, use the CPF contribution calculator, Foundific's take-home pay calculator or our take-home pay walkthrough.
CPF rate changes from 1 January 2027
From 1 January 2027, total CPF rates rise by 1.5 percentage points for ages above 55 to 60 and by 1 point for ages above 60 to 65. Rates for other ages stay the same.
| Your age | Employer 2027 | Employee 2027 | Total 2026 | Total 2027 |
|---|---|---|---|---|
| 55 and below | 17% | 20% | 37% | 37% |
| Above 55 to 60 | 16.5% | 19% | 34% | 35.5% |
| Above 60 to 65 | 13% | 13% | 25% | 26% |
| Above 65 to 70 | 9% | 7.5% | 16.5% | 16.5% |
| Above 70 | 7.5% | 5% | 12.5% | 12.5% |
Source: 2027 senior worker rate changes, applying to wages earned from 1 January 2027.
The increase goes to your RA up to the Full Retirement Sum, or to your OA if you have already set that sum aside (CPF Board). Employers get a CPF Transition Offset worth half of the 2027 increase in employer contributions, applied automatically.
At S$5,775 a month and age 58, your share rises from S$1,039 in 2026 to S$1,097 in 2027 (S$5,775 x 19% = S$1,097.25, rounded down).
Your pay after employee CPF falls from S$4,736 to S$4,678, while the total going into CPF rises from S$1,964 to S$2,050.
CPF contributions for PRs in the first two years
New PRs contribute at lower graduated rates for the first two years of PR status, then pay full rates from the third year. There are two sets of graduated rates.
| PR year (age 55 and below) | Employer | Employee | Total | Max employee share a month |
|---|---|---|---|---|
| Year 1, graduated (G/G) | 4% | 5% | 9% | S$400 |
| Year 2, graduated (G/G) | 9% | 15% | 24% | S$1,200 |
| Year 1, full employer (F/G) | 17% | 5% | 22% | S$400 |
| Year 2, full employer (F/G) | 17% | 15% | 32% | S$1,200 |
| Year 3 onwards | 17% | 20% | 37% | S$1,600 |
Rates are from Tables 2 to 5 of the 2026 rate table. The 2027 changes do not alter first- and second-year PR rates. Check with your employer which table applies to you.
Which payments attract CPF
Most cash you receive for your work attracts CPF, including allowances, overtime, commissions and bonuses. Genuine reimbursements of expenses do not.
| Attracts CPF | Does not attract CPF |
|---|---|
| Monthly salary | Reimbursed business or official travel expenses |
| Fixed transport and monthly meal allowances | Medical and training reimbursements |
| Overtime and extra duty pay | Gifts in kind |
| Commissions | Retrenchment and other termination benefits |
| Annual Wage Supplement (AWS) and bonuses, as Additional Wages | Work injury compensation |
| Payment in lieu of leave | Meal reimbursement for overtime |
Source: payments that attract CPF and common employer mistakes. An allowance that forms part of your wage attracts CPF, even a fixed S$150 transport allowance. For how these lines show up on a payslip, see gross vs basic vs net salary.
When CPF is due, and what to do if your employer doesn't pay
CPF for a month is due on the last day of that month, and employers who pay by the 14th of the following month avoid enforcement action. Your employer pays both shares and recovers your share from your salary.
Late payment draws interest of 1.5% a month. A first offence of not paying can lead to a fine of S$1,000 to S$5,000, up to six months' jail, or both.
An employer who deducts your share and doesn't pay it faces a fine of up to S$10,000, up to seven years' jail, or both.
If contributions look missing or wrong:
- Check your CPF statement against your payslip. Contributions are required if you earn more than S$50 a month (CPF Board).
- Ask your employer first, since delays and admin errors happen.
- If the answer doesn't resolve it, lodge a report with your payslips and employment contract. Act quickly: recovering payments more than a year old is unlikely.
Work it out with Foundific's take-home pay calculator
Enter your gross monthly pay, age and residency in Foundific's take-home pay calculator to see your employee CPF, your employer's CPF and what reaches your bank account at 2026 rates.
It also covers PR rates in the first two years and estimates your annual income tax.
Frequently asked questions
How much is the employer CPF contribution in 2026?
For employees aged 55 and below earning above S$750 a month, the employer CPF contribution is 17% of wages, on top of your salary. With the S$8,000 Ordinary Wage ceiling, the most an employer pays on monthly salary is S$1,360. The employer rate is 16% for ages above 55 to 60, 12.5% above 60 to 65, 9% above 65 to 70 and 7.5% above 70.
Do PRs pay the same CPF contribution as citizens?
Not at first. In the first year of PR status, the graduated rates are 4% from the employer and 5% from the employee, and in the second year 9% and 15%. Some employers pay the full 17% employer rate during those years instead. From the third year of PR status onwards, PRs contribute at the same rates as Singapore Citizens, which is 37% in total for age 55 and below.
What is the CPF submission deadline?
CPF contributions for a month are due on the last day of that month. Employers who pay by the 14th of the following month avoid enforcement action, and the deadline moves to the next working day if the 14th falls on a weekend or public holiday. Late payments are charged interest of 1.5% a month.
Is CPF deducted from my bonus?
Yes. Bonuses and the AWS are Additional Wages and attract CPF at the same rates as your salary, so at age 55 and below you pay 20% and your employer pays 17%. CPF on bonuses is capped by the Additional Wage ceiling, which is S$102,000 minus your Ordinary Wages subject to CPF for the year, so for high earners only part of a bonus may attract CPF.
Will CPF contribution rates change in 2027?
Yes, for senior workers. From 1 January 2027, the total rate rises to 35.5% for ages above 55 to 60 (16.5% employer, 19% employee) and to 26% for ages above 60 to 65 (13% each). Rates for age 55 and below and above 65 do not change, and the extra contributions go into your Retirement Account up to the Full Retirement Sum.
Related guides
This guide summarises the rules for employees covered by Singapore's Employment Act as of 27 October 2026. Your contract may give you more. For your specific situation, check with MOM, CPF Board or IRAS.